PlanningBy Stephanie Werner · August 2026 · 10 min read

How to Close Accounts After a Death: What Every Company Actually Requires

Closing accounts after a death is one of the most exhausting parts of settling an estate. Every company has different rules, some are helpful, and some aren’t. This guide tells you exactly what to expect and how to track it all.

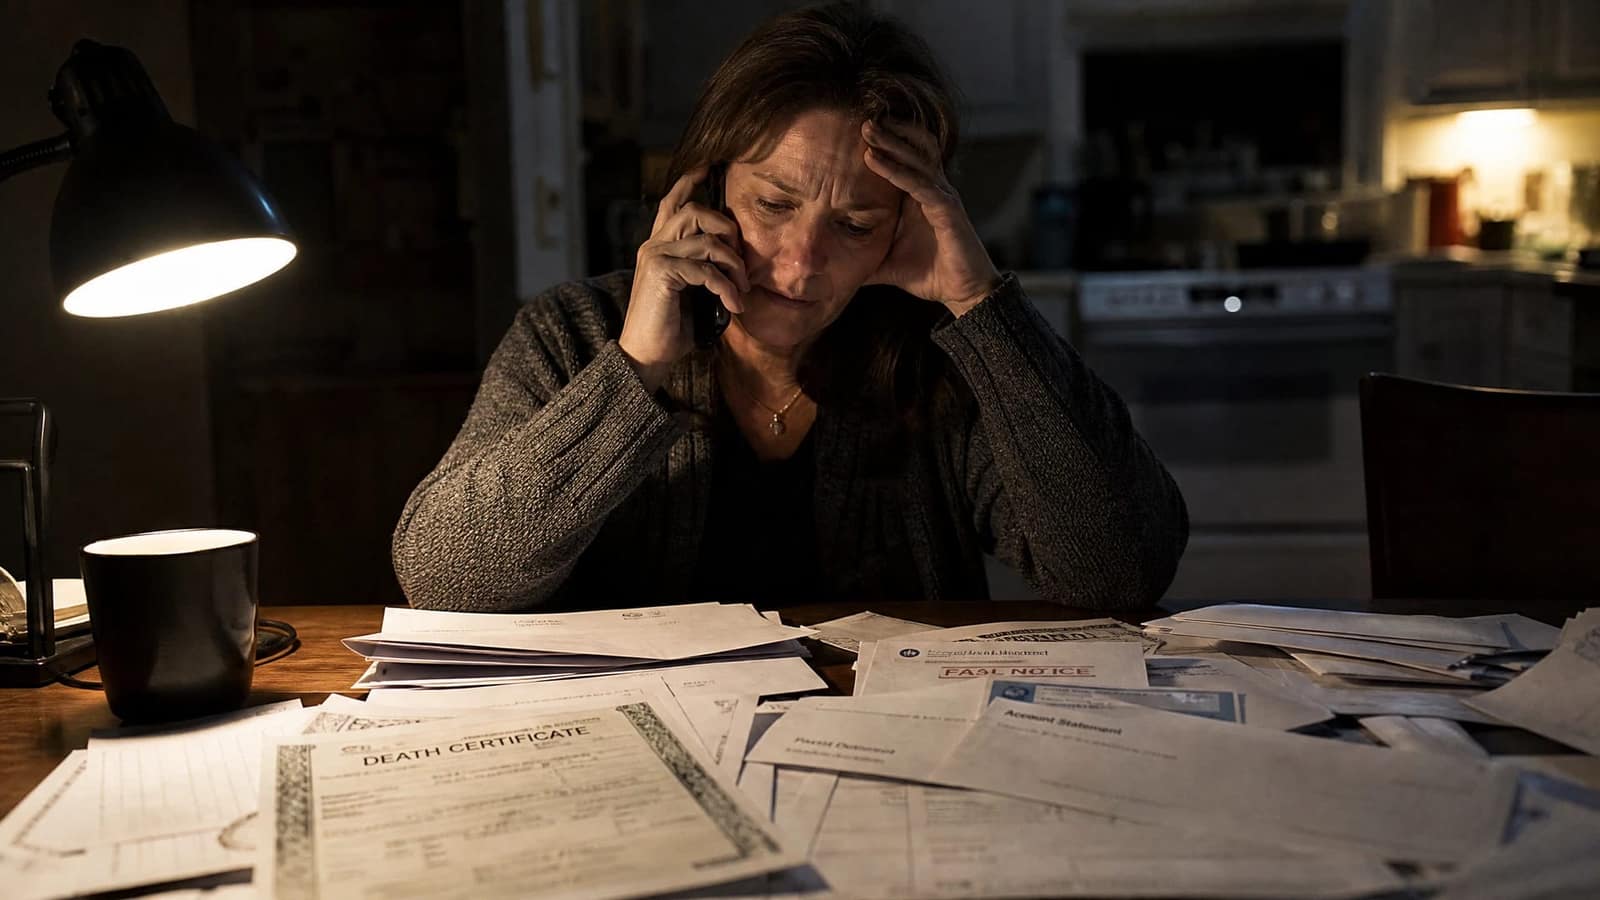
A person speaks on the phone while sorting bills and account papers

The Reality Nobody Warns You About

Closing accounts after a death is one of the most exhausting, maddening, and emotionally draining tasks you’ll face. If you've been named executor, the full scope of what an executor does goes well beyond accounts. But this is one of the most time-consuming parts. And if you're new to all of this, the paperwork nobody warned you about is worth reading first. You’re already grieving. And now you have to call Spectrum.

Every company has its own rules. Some are genuinely helpful. They have a dedicated bereavement team, they waive early termination fees, they process everything in one call. Others will put you on hold for 45 minutes, transfer you three times, and then tell you that you need to fax a notarized copy of the death certificate to an address that no longer exists.

This guide won’t sugarcoat it. But it’ll tell you exactly what to expect from each type of account, what documents to have ready, and how to track your progress so nothing gets missed.

To work through the notifications as a checklist that saves your place, use our free Who to Notify tracker.

What You Will Need Before You Start

Before you make a single call, gather these items. Having them ready will save you from calling back a second time.

Death certificates: There’s no universal number. List the banks, insurers, courts, agencies, property offices, and other institutions you expect to contact. Ask each one whether it needs a certified copy or accepts another format, then order an initial quantity based on those actual needs. Confirm the current fee and how to order more.

Account numbers: Look through recent statements, emails, and the deceased's files. If you can’t find an account number, the company can usually look it up by name, Social Security number, or address.

Your own ID: You’ll need to prove who you are, especially when taking over or closing accounts where the deceased was the primary holder.

Legal authority: If you’re the executor of the estate, have a copy of the Letters Testamentary (issued by the probate court). If the account was joint, you may not need this; your name is already on the account. If there was a living trust, the successor trustee documents will be needed.

A tracking system: A spreadsheet, a notebook, or the Account Tracker in your MORTL dashboard. You need to record the date of every call, the name of every representative you spoke with, what was agreed, and what the next step is. You’ll thank yourself later.

Banks and Credit Cards

Banks and checking/savings accounts

If the account was joint, don’t assume that it automatically continues unchanged. The account agreement and state law determine what the surviving account holder can do. Contact the bank, report the death, and ask what documents it needs and whether it will keep the account open, restrict it, or open a replacement account [2].

If the deceased was the sole account holder, who can access the funds depends on any payable-on-death beneficiary, the estate's probate status, state small-estate procedures, and the bank's policy. A court-appointed personal representative often needs Letters Testamentary or Letters of Administration to act for the estate [4]. A named beneficiary may use a different claim process.

Many states offer a small-estate procedure, but the eligibility rules, waiting periods, dollar limits, and documents vary. Check the current court or probate guidance for the state where the estate is being handled before relying on a threshold.

Credit cards

If the deceased was the primary cardholder and you were an authorized user, stop using the card and call the issuer. Being an authorized user alone generally doesn’t make you liable for the balance. Responsibility can be different for a joint account holder, co-signer, spouse under applicable state law, or the estate. Ask the issuer what status its records show, and get legal guidance if liability is unclear.

If you were a joint account holder, contact the issuer promptly to confirm responsibility for the balance and whether the account can continue in your name.

What to say: "I’m calling to report the death of [name], account number [number]. I’m the [executor/spouse/next of kin]. I’d like to [close the account / transfer it to my name]."

Most major banks have a dedicated estate services team. Ask to be transferred to them. They handle this regularly and are usually more efficient than general customer service.

Utilities and Home Services

Electric, gas, and water

If you’re staying in the home, call the utility and ask how to transfer or replace the account without interrupting service. Document and credit requirements vary. Ask whether any deposit, final bill, or contract fee applies before agreeing to the change.

If the home is being sold or vacated, you can close the account. Give them a final date and ask for a final bill.

What to watch for: Automatic payments set up from the deceased's bank account will stop working once that account is closed. Make sure you set up new payment methods before the account is transferred.

Home security systems

These services may have contracts with early termination fees. Ask whether the provider offers a death-related cancellation process or fee waiver. Policies vary. Get the answer in writing, or record the representative's name and the date of the call.

Lawn care, cleaning services, and other recurring home services

Contact each provider and ask what it requires to close or transfer the service. Don’t send a certified death certificate unless the provider says it needs one. Update or stop automatic payments only after confirming who has authority over the payment account.

Phone, Cable, and Internet

Telecom account processes vary. Before calling, gather the account number, decide which services should continue, and ask whether the company has an estate or bereavement team.

Mobile phone

If the deceased was the primary account holder and you were on a family plan, ask the carrier how to transfer billing responsibility without interrupting the other lines. Document requirements vary. Protect the deceased person's Social Security number and provide it only through a verified carrier process when it's required.

If the deceased had an individual line you want to cancel, call the carrier, report the death, and request its deceased-customer process. Ask explicitly about device balances, contract fees, number transfers, and equipment returns. Document the answer.

Cable and internet

If you want to keep the service, transfer it to your name. If you want to cancel, call and report the death. Return any equipment (cable boxes, routers) or you’ll be charged for it.

If the process stalls: Ask for an estate, bereavement, or account-specialist team. Record every interaction. If a regulated provider won’t explain its process or resolve a documented error, check the appropriate state or federal consumer complaint channel before filing a complaint.

Subscriptions and Digital Services

Streaming services (Netflix, Hulu, Spotify, etc.)

These are usually the easiest. Log into the account, go to account settings, and cancel. If you don’t have the password, use the "forgot password" option with the deceased's email address. If you can’t access the email, contact the streaming service directly. Most have a process for this.

Amazon

Amazon accounts may include a Prime membership, gift-card balance, orders, and digital purchases. Do not access or close the account unless you’re authorized. Contact Amazon through its verified customer-service channel and ask for its current deceased-customer process. Transferability and refunds depend on the account terms and the specific balance or purchase.

Apple ID / iCloud

Apple has a Digital Legacy program that allows designated legacy contacts to access the account after death. If the deceased didn’t set this up, you’ll need to contact Apple with the death certificate and a court order in most cases. This is worth pursuing if there are important photos or documents stored in iCloud.

Google / Gmail

Google's Inactive Account Manager allows users to designate what happens to their account after death. If this wasn’t set up, you can submit a request through Google's deceased user process with the death certificate.

Subscription boxes and recurring orders

Check the deceased's email for subscription confirmation emails. Search for "your subscription," "your order," "renewal," and "receipt." Cancel each one individually. Check the bank and credit card statements for recurring charges you may have missed.

Government Accounts

Social Security

Funeral homes generally report a death to the Social Security Administration, but confirm that the report was made. Social Security can’t pay a benefit for the month of death or any month after it, and benefits are paid a month behind. So the payment that lands after a death is usually the month-of-death benefit and has to go back. A payment covering a month the person lived all the way through is still due. Don’t move, spend, return, or cash it until SSA or the bank confirms the benefit month [3].

If you’re a surviving spouse or dependent child, you may be eligible for survivor benefits. Contact SSA at 1-800-772-1213 or visit your local office [3].

Medicare

If the deceased had Medicare, notify the Social Security Administration. They will handle the Medicare notification [1]. Return any Medicare Advantage or Part D plan cards.

Veterans benefits

If the deceased was a veteran, notify the Department of Veterans Affairs. Surviving spouses and dependents may be eligible for benefits including Dependency and Indemnity Compensation (DIC), burial benefits, and survivor pension.

Driver's license and voter registration

Notify your state's DMV to cancel the driver's license [1]. Many states also allow you to notify the voter registration office to remove the deceased from the rolls.

Passport

The State Department recommends canceling or returning the passport of a deceased U.S. citizen [1]. Mail it to the State Department with a copy of the death certificate and a note requesting cancellation.

Insurance Policies

Life insurance

This isn’t a cancellation. It’s a claim. Contact the insurance company and ask for its current claim instructions. The insurer will explain which documents it needs. Payment timing varies by state law, insurer, policy terms, and whether the claim requires additional review.

Health insurance

If the deceased was the primary insured and other family members were covered under the plan, contact the employer or plan administrator immediately and ask for the exact coverage end date and written continuation options. COBRA and Marketplace special-enrollment windows use different rules and notices. Confirm the deadline that applies before coverage ends [5].

Auto insurance

If you’re keeping the vehicle, contact the insurer to transfer the policy to your name. If you’re selling or surrendering the vehicle, cancel the policy. Don’t cancel before the vehicle is sold or transferred. You need coverage until the title changes hands.

Homeowner's or renter's insurance

Contact the insurer to update the policy to your name. If the home is going through probate and will be vacant for an extended period, notify the insurer. Vacant homes often require a special endorsement.

How to Track Everything

The beta tester who inspired this article said it best: "You make a list and keep track of what you need to do, what is in progress (who you talked to, their number and what else you need to do), what has been closed/cancelled and what is now new in only your name."

That’s exactly right. You need four columns:

1. To Do. Every account you know about that still needs action 2. In Progress. Accounts you’ve contacted, with the rep's name, phone number, what was agreed, and what the next step is 3. Closed/Cancelled. Accounts that are done 4. Transferred to My Name. Accounts that are now in your name only

The MORTL Account Tracker in your dashboard is built for exactly this. You can add every account, track its status, log every call with the date, rep name, phone number, outcome, and next step. And export the whole thing to PDF when you need a record for the estate attorney or probate court.

One more tip: When a company tells you something important (that they’re waiving a fee, that they’ll process the cancellation in 5 to 7 days, that you don’t need to return equipment), write it down immediately. Get the representative's name and employee ID if possible. This documentation protects you if the company later claims the conversation never happened.

The Emotional Reality

There’s no way to make this process easy. You’re going to be put on hold while grieving. You’re going to have to explain, over and over, that someone you loved has died. You’re going to encounter representatives who are genuinely kind and helpful, and others who seem designed to make your life harder.

Give yourself permission to stop when you need to. You don’t have to do this all in one day, or one week. Most accounts can wait. The ones that can’t, Social Security, health insurance, and the estate bank account, are noted above.

Take breaks. Ask for help. If you have a family member or trusted friend who’s good at this kind of administrative work, let them make some of the calls. There’s no rule that says you have to do it alone.

And when it’s done, when every account is closed, transferred, or cancelled, know that you did something genuinely hard, logistically and emotionally. That matters.

Sources & References

Research & Citations

All factual claims in this article are sourced from peer-reviewed research, government data, and named institutions. Citations follow APA 7th edition format.

  1. [1]USAGov. (2024). Agencies to notify when someone dies. ↗ Source Retrieved July 2, 2026
  2. [2]Consumer Financial Protection Bureau. (2023). What happens if I have a joint bank account with someone who died?. ↗ Source Retrieved August 1, 2026
  3. [3]Social Security Administration. (2026). What You Need to Know When You Get Retirement or Survivors Benefits. ↗ Source Retrieved August 1, 2026
  4. [4]Legal Information Institute, Cornell Law School. (2025). Letters testamentary. Wex. ↗ Source Retrieved July 29, 2026
  5. [5]U.S. Department of Labor. (2026). Continuation of Health Coverage (COBRA). ↗ Source Retrieved August 1, 2026

Share this story

Post it, or send it straight to the person who needs it. The link goes with it.

Keep Reading

Law & Policy

Transfer on Death Deed: The Deed Most People Have Never Heard Of

One document. Recorded before you die. Your house bypasses probate entirely. No court, no waiting, no attorney fees.

9 min read
Law & Policy

How Long Does Probate Take? The Deadlines That Set the Clock

Probate timing depends on state law, creditor periods, assets, taxes, disputes, and court workload. This FAQ explains the milestones that control the calendar.

12 min read
Planning

What Does an Executor Actually Do?

An executor gathers records, protects estate property, handles probate, pays valid debts and taxes, reports to beneficiaries, and distributes what remains.

10 min read
Law & Policy

Social Security Survivor Benefits: Eligibility, Payments, and How to Apply

Social Security has monthly survivor benefits and a one-time death payment. Eligibility depends on the worker's record and the survivor's relationship, age, disability status, and other facts.

8 min read
Law & Policy

What Happens to a Joint Bank Account When Someone Dies?

The account agreement, account title, state law, and any payable-on-death designation determine who owns the money and who can access it after a death.

8 min read

The Death Dispatch

More stories like this, weekly.

A newsletter about death you'll actually look forward to reading.